ATAD
Various measures to fight against aggressive tax planning have been introduced by the Luxembourg law of 21 December 2018 (the “ATAD Law”), which, among others, implemented the Council Directive (EU) 2016/1164 of 12 July 2016 (commonly known as “ATAD”). Whilst introduced already on 1 January 2019, these measures will, from a Luxembourg tax structuring perspective, still play in 2020 a crucial role for existing and new structures. They include the following:
• the controlled foreign companies rules,
• the interest deduction limitation rules,
• the hybrid mismatches rules,
• the general anti-abuse rules,
• a reinforcement of the permanent establishment concept in a double tax treaty context, and
• the abolition of the tax neutral conversion of a debt into equity.
The ATAD Law has further introduced new exit taxation rules (including new valuation rules regarding transferred assets), which are applicable as from this year only.
ATAD 2
The hybrid mismatches rules introduced by the ATAD Law have been extended to a broader range of transactions as well as to transactions with non-EU countries by means of the Luxembourg law of 20 December 2019 (the “ATAD 2 Law”), which implemented the Council Directive (EU) 2017/952 of 29 May 2019 (commonly known as “ATAD 2”).
The ATAD 2 Law, mostly applicable as of 1 January 2020, deals with eleven scenarios of hybrid mismatches:
1. hybrid mismatches that result from payments under a financial instrument,
5. hybrid mismatches that result from payments made by a hybrid entity to its owner,
8. imported hybrid mismatches,
11. reverse hybrid mismatches.
DAC 6
In 2020, Luxembourg will also implement the EU Directive 2018/822 of 25 May 2018 (commonly known as “DAC 6”) into domestic law. DAC 6 aims to exchange at EU level information on arrangements, which could be considered as aggressive operations from a tax perspective. In this context, the DAC 6 Law will require certain persons to report specific arrangements, which may be considered as harmful in the context of a fair taxation.
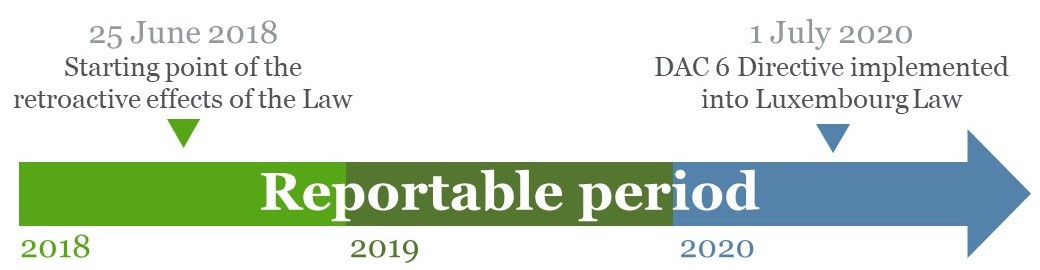
DAC 6 reportable period Hogan Lovells
This law, which should be applicable as of 1 July 2020, is already now playing a major role for many professionals in Luxembourg as it will have a retroactive effect up to 25 June 2018.
You have a question regarding any of the topics above? Contact our tax team for further information.
Gérard Neiens, Jean-Philippe Monmousseau, Pierre-Luc Wolff et Grâce Mfuakiadi. Hogan Lovells